

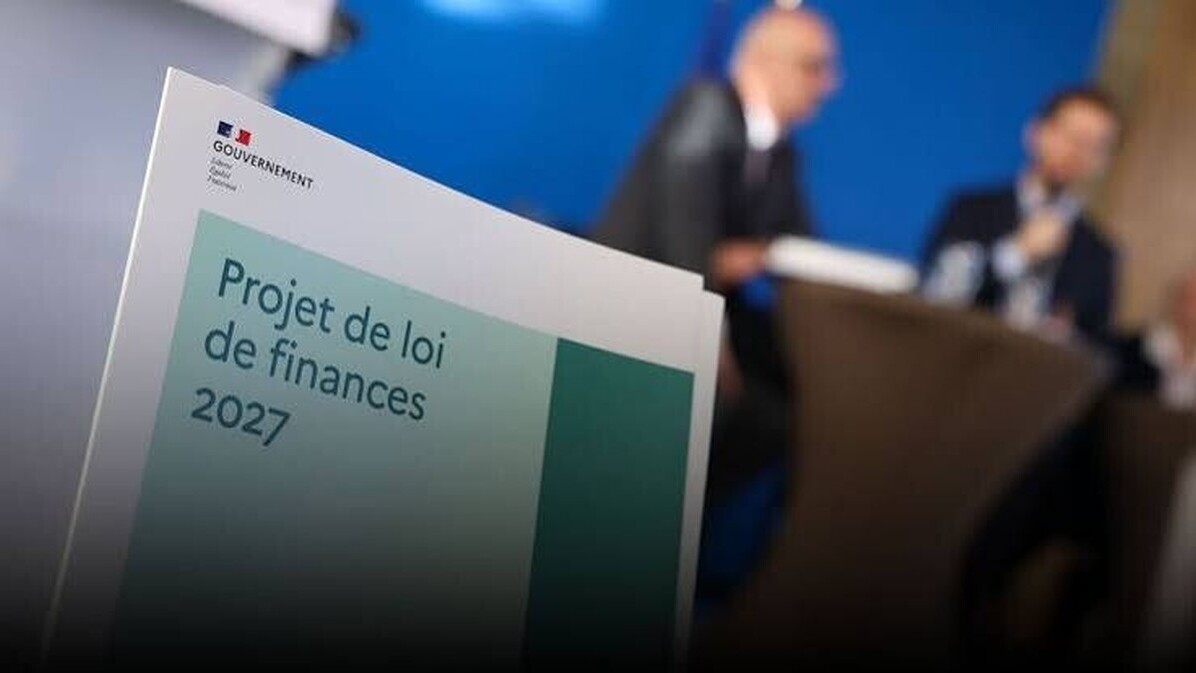
The Banque de France calls on political leaders to adopt a credible budget and commit to a sustainable reduction of the public deficit. Its governor, Emmanuel Moulin, believes that controlling national finances is primarily a French responsibility. This reminder comes as budgetary tensions fuel concerns about debt and interest rates.
The state of French public finances remains a major concern ahead of the 2027 budget review. The governor of the Banque de France, Emmanuel Moulin, emphasized the need to restore investor and household confidence by presenting a sustainable budget trajectory. For the institution, adopting a budget before the end of the year is an essential step, but it will not suffice if deficit reduction commitments are not followed by results.
The government’s target of reducing the public deficit to 5% of GDP by 2027 is considered by Emmanuel Moulin as a realistic but modest first step. The Banque de France views this as an upper limit not to be exceeded. After a deterioration of accounts in 2026, notably in a context of slower growth, authorities must convince that public debt can be stabilized in the medium term.
The ECB does not replace national budgetary decisions
The European Central Bank has monetary instruments allowing it to act on financing conditions within the eurozone. It sets key interest rates and can, under certain circumstances, intervene to prevent unjustified disruptions in the transmission of its monetary policy. However, its mandate does not include financing member states’ deficits nor unconditionally guaranteeing their borrowings.
This distinction is essential in the French case. An increase in the rates at which France borrows can result from several factors, including monetary policy expectations, economic conditions, and perceptions of budgetary risk. Any potential intervention by the ECB would therefore not exempt the government from presenting a credible strategy to control expenditures and revenues.
The cost of debt becomes a central issue
When investors demand higher compensation to lend to a state, the cost of new debt issuances rises. This increase gradually passes on to interest charges as maturing borrowings are renewed. For France, which has significant debt, a sustained rise in rates can reduce the margins available to finance public policies.
The problem is not limited to state finances. Sovereign financing conditions also indirectly influence those of banks, businesses, and households. A prolonged deterioration of confidence could therefore weigh on investment and economic activity. This is why the Banque de France stresses the need to combine budgetary credibility with support for growth.
A political debate on ways to reduce the deficit
It remains to be determined how to achieve the announced objectives. Different political forces disagree on how to share the effort between spending cuts, tax changes, and measures aimed at stimulating activity. These trade-offs will have direct consequences on public services, businesses, and household purchasing power.
The Banque de France’s message does not constitute a detailed budget program. It mainly reminds that financial stability depends on decisions made at the national level. Ahead of parliamentary deadlines, the government must therefore seek an agreement to adopt the budget while providing visibility on debt evolution. The ECB can contribute to monetary stability in the eurozone, but it cannot substitute for this political responsibility.




Respond to the article
Be the first to comment on this article.